Mortgage Valuation Reports in India: Why Banks Require Them
Getting a home loan in India is a significant financial step, and if you have applied for one, you have likely heard your bank mention a "mortgage valuation report." This report is not just a formality; it is a critical document that plays a central role in your loan approval process.
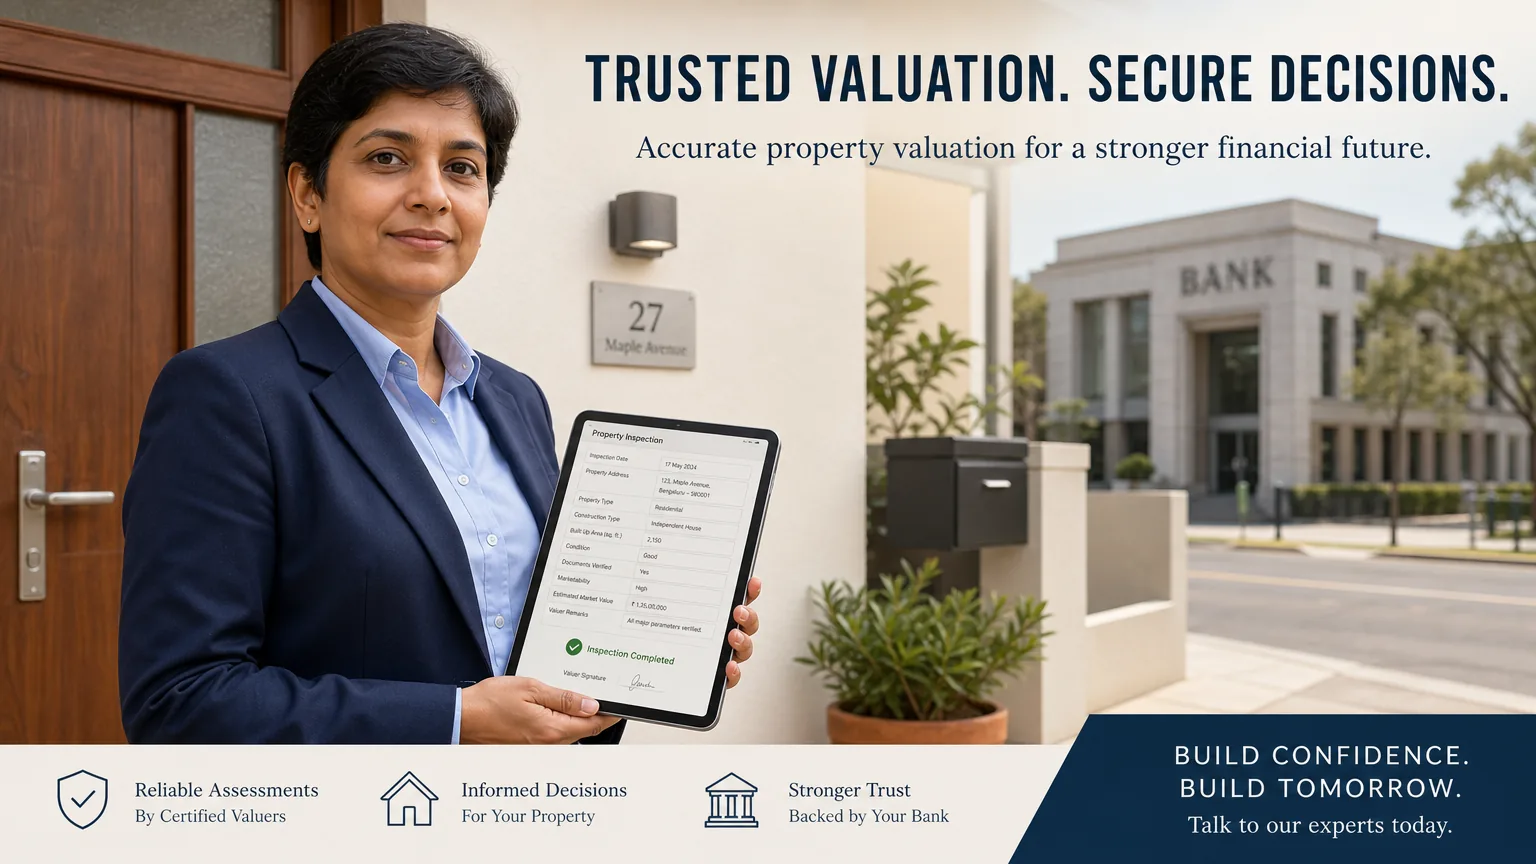
A mortgage valuation report is a professional assessment of a property's market value, conducted by a government-approved valuer. Banks in India require this report to verify that the property's value is sufficient to act as collateral for the loan amount, protecting them from financial loss in case of a default.
Getting a home loan in India is a significant financial step, and if you have applied for one, you have likely heard your bank mention a "mortgage valuation report." This report is not just a formality; it is a critical document that plays a central role in your loan approval process. As government-approved property valuers since 1995, we understand these reports. Many people are unsure about the report's purpose and what the process involves. This guide will explain everything in plain language.
What is a Mortgage Valuation Report?
A mortgage valuation report is an independent assessment of a property's market value. It is prepared by a qualified and government-approved property valuer. The report provides a detailed analysis of the property, including its location and condition, which influence its value in the current market.
The Core Purpose: Securing the Bank's Investment
Think of a home loan as a partnership. You get the funds to buy a property, and the bank takes on a risk. To manage this risk, the property you are buying acts as collateral. This means if you are unable to repay the loan, the bank has the right to sell the property to recover its money.
The mortgage valuation report is the bank's way of confirming that the collateral is worth enough to cover the loan amount. It helps the bank determine the Loan-to-Value (LTV) ratio. The LTV ratio is the percentage of the property's value that the bank is willing to lend. For example, if a property is valued at Rs. 1 Crore and the bank offers an 80% LTV, they will lend up to Rs. 80 Lakhs. The valuation ensures the bank is not lending more than the property is actually worth, protecting their investment.
What a Mortgage Valuation Is Not
It is important to understand that a mortgage valuation is not the same as a structural survey or a home inspection. While a valuer will note obvious defects that impact value, their primary focus is on the property's market worth.
- Mortgage Valuation: Focuses on the market value of the property for lending purposes. It is a brief inspection to confirm the property's general condition and features that affect its value.
- Structural Survey/Home Inspection: This is a much more detailed examination of the property's physical condition, highlighting any structural issues, dampness, roof problems, or other defects. This report is for your benefit as a buyer, to understand the property's condition and potential repair costs before you commit to buying.
So, while a mortgage valuation might flag a major structural problem if it significantly impacts value, it will not examine the finer details of the property's construction or maintenance needs like a full structural survey would.
Why Every Bank in India Requires a Valuation Report for a Home Loan
All banks and housing finance companies in India will insist on a property valuation report before sanctioning a home loan. This is not arbitrary; it is rooted in sound financial practice and regulatory requirements.
Risk Mitigation for the Lender
Banks are in the business of lending money responsibly. When they lend for a home, they need to ensure they can recover their funds if the borrower defaults. The valuation report is their primary tool for assessing this risk.
The Reserve Bank of India (RBI) issues strict guidelines for banks regarding asset classification and provisioning. If a loan goes bad, the bank has to set aside capital to cover potential losses. A robust valuation ensures that the collateral held against the loan is adequate, minimizing the bank's exposure to risk. If the property's value is lower than the loan amount, the bank faces a greater loss in a default scenario. Banks prioritize accurate valuations to manage their balance sheets effectively and comply with RBI norms.
Legal and Regulatory Compliance
Beyond internal risk management, banks operate under a strict legal and regulatory framework. The SARFAESI Act, 2002 (Securitisation and Reconstruction of Financial Assets and Enforcement of Security Interest Act) is a key piece of legislation that allows banks to enforce security interests (like foreclosing on a property) without court intervention in case of a loan default.
For a bank to legally exercise its rights under the SARFAESI Act, a proper, independent valuation of the secured asset (the property) is the first and most crucial step. Without a credible valuation, the bank's ability to recover its dues through legal means would be severely hampered. This makes the valuation report not just a financial document, but a legal necessity.
Determining the Loan Amount
Many people assume the bank will lend based on the sale price mentioned in their agreement. However, the final loan amount is directly tied to the property's valuation, not necessarily the sale price.
If you are buying a property for Rs. 1.2 Crore, but the bank's valuer assesses its market value at Rs. 1 Crore, the bank will base its LTV calculation on the Rs. 1 Crore valuation. So, if their policy is an 80% LTV, your maximum loan amount would be Rs. 80 Lakhs, not Rs. 96 Lakhs (80% of Rs. 1.2 Crore). This difference is significant and can impact your financial planning. The valuation ensures that the bank is lending against a realistic market value, protecting both the bank and, indirectly, the borrower from over-indebtedness based on an inflated sale price.
The Mortgage Valuation Process: A Step-by-Step Guide
Understanding the steps involved in a mortgage valuation can help you prepare and know what to expect.
Step 1: The Bank Appoints a Valuer
Once your loan application progresses, the bank will initiate the valuation process. They typically have a panel of approved valuers they work with. These are firms or individuals who meet their criteria for professional expertise and regulatory compliance.
Rao Valuers is on the panel for many leading banks across India. When a bank assigns us a valuation, they provide us with the property details and the borrower's contact information. Note that you cannot usually choose your own valuer for a bank loan; the bank will appoint one from its approved list.
Step 2: The Physical Inspection
This is where the valuer visits the property. The purpose of this visit is to gather firsthand information about the property that will influence its value. As government-approved valuers since 1995, our process involves a thorough physical inspection where we look at several key aspects:
- Location: Proximity to essential services (like schools and hospitals), transport links, and the overall desirability of the neighbourhood.
- Size and Dimensions: Accurate measurement of the plot area, built-up area, and carpet area.
- Age and Condition: The age of the construction, its structural integrity, and the general state of maintenance.
- Layout and Design: Functionality of the floor plan, natural light, ventilation, and overall aesthetic appeal.
- Quality of Construction: Materials used, finishes, and the standard of workmanship.
- Amenities: Availability of parking, lifts, security, power backup, and other facilities.
- Legal Aspects: We also check for any visible encroachments or deviations from approved plans that could affect marketability or value.
The valuer will take photographs of the property's exterior and interior, along with the surroundings, to include in the report.
Step 3: Data Analysis and Market Comparison
After the physical inspection, the valuer returns to their office for detailed analysis. They use several valuation methods to arrive at an accurate market value:
- Sales Comparison Approach (Market Approach): This is the most common method. The valuer identifies recently sold properties that are similar to the subject property in terms of location, size, age, and features. They then adjust the prices of these comparable properties to account for any differences, arriving at a fair market value for your property.
- Cost Approach: This method estimates the cost to rebuild the property new, minus depreciation, plus the value of the land. It is often used for newer or unique properties where comparable sales are scarce.
- Income Approach: Primarily used for commercial or rental properties, this method estimates value based on the potential income the property can generate.
They also check local circle rates, which are the minimum prices at which a property can be registered in a particular area. While the market value is often higher than the circle rate, it serves as a baseline. We also cross-reference with recent transaction data and property market trends to ensure our valuation is current and robust.
Step 4: Compiling the Final Report
The final step is compiling a comprehensive report that presents the valuer's findings and conclusion. This report is then submitted directly to the bank. Key components of the final report include:
- Property Details: Address, legal description, plot area, built-up area, and other specifications.
- Purpose of Valuation: Clearly stating it is for mortgage purposes.
- Market Value: The final assessed market value of the property.
- Photographs: Visual evidence of the property's condition and features.
- Supporting Data: Details of comparable sales or other data used in the analysis.
- Valuer's Certification: A declaration by the government-approved valuer, including their registration numbers (like IBBI/RV/02/2019/10843), confirming the independence and accuracy of the report.
As part of our ISO 9001 certified process, we ensure every report is delivered within 48 to 72 hours, providing banks with the information they need quickly.
Choosing a Property Valuer: What to Look For
While banks typically appoint their own valuers for home loans, understanding what makes a good valuer is important for other valuation needs, such as capital gains valuation or visa applications, where you might directly engage a valuer.
Key Credentials for Bank Valuations in India
For any property valuation that must be accepted by official bodies like banks, the Income Tax Department, or courts, certain credentials are non-negotiable.
- Government Approved Valuer Status: This is fundamental. A government-approved valuer is licensed by the government to conduct valuations for official purposes. Rao Valuers has been government approved since 1995.
- IBBI Registered Valuer Status: The Insolvency and Bankruptcy Board of India (IBBI) regulates valuers, ensuring they meet stringent professional and ethical standards. An IBBI registered valuer has undergone specific training and examination. We are IBBI registered valuers.
- ISO 9001 Certification: This certification shows the valuation firm follows international standards for quality management. It means their processes are consistent and well-documented. Rao Valuers is ISO 9001 certified.
These credentials ensure that the valuation report is credible and will be accepted by all relevant authorities.
Comparing Valuation Service Providers
When you need a valuation, you might encounter different types of providers. Here is an honest comparison to help you understand the landscape:
| Feature | Rao Valuers | Approved Valuers (Competitor) | Local/Individual Valuer |
|---|---|---|---|
| Govt. Approval | Yes, since 1995 | Typically, yes | Varies, must be verified |
| IBBI Registration | Yes | Often, yes | Less common, depends on individual |
| Service Area | Pan-India | Often city-specific or regional | Hyper-local, usually one city |
| Report Turnaround | 48-72 hours | Varies, often 3-5 days | Highly variable |
| Bank Panel Status | On panels of most major banks | On panels of some local/regional banks | May be on a few local branch panels |
| Process Standard | ISO 9001 Certified | Not typically advertised | No formal certification |
This table highlights that while many valuers are government approved, not all offer the same level of service, geographical reach, or process standardization. For critical financial decisions, these differences matter.
Frequently Asked Questions (FAQ) about Mortgage Valuations
Here are some common questions people have about mortgage valuation reports:
Question: Who pays for the mortgage valuation report?
Answer: In most cases, the borrower (you) is responsible for paying the valuation fee. This fee is typically collected by the bank and then paid to the valuer. It is part of the overall loan processing charges.
Question: What happens if the valuation is lower than the property's sale price?
Answer: If the valuation comes in lower than your agreed sale price, it means the bank will lend you less than you anticipated. For example, if you agreed to buy a property for Rs. 1 Crore, but it is valued at Rs. 90 Lakhs, and the bank offers an 80% LTV, your loan amount will be Rs. 72 Lakhs (80% of Rs. 90 Lakhs) instead of Rs. 80 Lakhs (80% of Rs. 1 Crore). You will then need to arrange for the difference from your own funds or renegotiate the sale price with the seller.
Question: Can I use my own valuation report for a bank loan?
Answer: Generally, no. Banks insist on appointing their own valuer from their approved panel. This is to ensure independence and impartiality. They want a report from a valuer they trust and who adheres to their specific reporting standards.
Question: How long is a mortgage valuation report valid for?
Answer: The validity period for a mortgage valuation report can vary between banks, but it is typically between three to six months. Property markets can change rapidly, so banks need recent valuations to ensure the collateral's value is current. If your loan process extends beyond this period, the bank might request a re-valuation.
Question: Does a high valuation mean the property is a good investment?
Answer: A high valuation from a bank simply means the property has a strong market value for lending purposes. It does not automatically mean it is a good investment in terms of future appreciation or rental yields. Investment decisions require a broader analysis of market trends, potential for growth, and your personal financial goals. A capital gains valuation, for example, looks at historical value for tax purposes, which is a different angle.
Question: What documents should I have ready for the valuer?
Answer: While the valuer will primarily inspect the property, having certain documents ready can help. These might include property ownership documents (sale deed, title deed), approved building plans, property tax receipts, and any society or maintenance records. The valuer might ask for these to verify details or assess any potential legal or structural issues.
If your bank has requested a valuation report for your home loan, or if you have questions about the process, our team of government-approved valuers is here to help. Get a free, no-obligation quote: https://raovaluers.in/contact
Checked by Parish Rao, Chartered Engineer and Government Approved Valuer (Registration number CAT-I/443/117/2000-01).
Page last checked on 8 November 2026.
Get a free valuation quote
Tell us what you need valued. We will message you on WhatsApp with which report you need and what it costs, free of charge.
In a hurry? Call +91 98681 69747 instead.